

Payactiv analysis by Appwee
Managing money is difficult enough without having to wait for the next regular payday when an urgent bill appears. I found Payactiv most useful as a finance app built around that exact pressure: it gives eligible workers a way to access wages they have already earned and use that breathing room while working toward better financial habits. That makes it different from a conventional budgeting app, which mainly shows where money went, and from a loan app, which advances borrowed money.
In my experience, the appeal is straightforward. Payactiv is free to download, aimed at Everyone, and developed by On-demand pay and beyond. It has been available since June 4, 2014, and its current version is 2.2.8 for devices running operating system 10 or later. Its public store presence is substantial, with over a million installs, an average rating of 4.4 from around forty-five thousand ratings, and about nine thousand reviews. Those figures suggest that many people find the idea useful, although they should not replace checking whether your employer and personal circumstances support the service.
How Payactiv feels to use when money is tight
Readability and navigation that keep the main task visible
The most important quality in an earned-wage app is not visual decoration; it is whether I can understand what I can access and what action comes next. Payactiv’s purpose is easier to grasp than the broader promise of many personal-finance apps. Instead of making me build a complete financial plan before seeing value, it focuses attention on wages earned early and financial wellness goals.
That focus can be reassuring for someone who is already stressed. A person checking the app before a utility payment does not necessarily want a lesson about compound interest or a long list of spending categories. They need to know whether the available balance is relevant, what using it means for the next payday, and which step leads forward. I would still recommend reading every explanation and confirmation screen carefully rather than treating a prominent amount as free extra money.
For readability, the app is most helpful when I use it deliberately instead of opening it in a rush. I would increase the phone’s text size if needed, keep the display uncluttered, and pause before confirming a transfer or financial action. Those are simple habits, but they matter because a small misunderstanding in a money app can have a larger consequence than a missed button in an entertainment app.
The app’s financial-wellness angle also changes how I judge navigation. A good path should not end at “get money now.” It should help me connect an immediate decision with the next pay cycle and a longer-term goal. That is a meaningful distinction: early wage access can solve a timing problem, but it does not automatically solve an income problem. I see Payactiv as most responsible when I use it occasionally and understand the effect on my normal cash flow.
Motor and sensory considerations in everyday use
People interact with finance apps in very different ways. Some use one hand while commuting, some rely on enlarged text, some have limited dexterity, and others are sensitive to dense screens, small controls, or sudden visual changes. I cannot treat Payactiv as equally comfortable for every person, but I can say what I would do to make the experience more manageable.
I would use the phone’s built-in accessibility tools, including larger text, stronger contrast, screen magnification, voice control, or a screen reader where those tools fit my needs. I would also avoid completing a transaction while walking, carrying something, or dealing with a noisy environment. Financial confirmation deserves a stable setting because motor mistakes and sensory overload are not merely inconveniences when an action affects available money.
For someone with limited hand movement, voice control may make navigation easier, but spoken commands are not a substitute for checking the final details visually or through an assistive technology. A user with low vision may benefit from system-level enlargement, yet enlarged content can sometimes require more scrolling. That creates a trade-off: bigger text improves recognition, while extra movement through the screen can make a short task feel longer.
Users with hearing loss should not need audio alone to understand a financial action. I would look for written status messages and save any confirmation details in a way I can review later. Users with cognitive disabilities may find the app easier if they complete one task at a time, write down the expected payday balance beforehand, and avoid switching between Payactiv and several other money apps during the same decision.
The safest accessibility habit is to make the amount and timing understandable before confirming anything. That advice is especially important for an app dealing with earned wages, because the money may feel familiar even though the timing of access is different from the timing of a regular paycheck.
Situational access: where the app fits and where it does not
Payactiv makes the most sense for a worker facing a short gap between an unavoidable expense and the normal payday. Imagine a grocery bill, transport cost, or household payment arriving after several shifts have already been completed but before the usual deposit. In that situation, I would first calculate the exact amount needed, then consider whether accessing only that amount would prevent a larger problem. Taking more simply because it is visible would weaken the benefit of the tool.
This is also where the app differs from a credit card or personal loan. A card may offer a familiar payment method but can leave a balance that carries forward. A loan may provide a larger amount but introduces borrowing and repayment considerations. Payactiv’s central idea is tied to wages already earned, so it can be a better fit for a timing mismatch than for a lasting shortfall. If my income is consistently too low for essential expenses, I would not rely on early access as the main solution.
Compared with a budgeting app, Payactiv is more immediate but less suited to building a complete picture of household finances. A budgeting tool can help me plan categories, monitor recurring bills, and compare months. Payactiv addresses the moment when earned income is not yet available in the ordinary way. I would use a budget alongside it, not instead of one, because seeing an earlier portion of wages does not by itself reveal whether the month is affordable.
Situational access also includes work and device context. A shift worker may check the app between jobs, while a parent may need to complete a task quickly with a child nearby. Someone with unreliable connectivity or an older device may find any finance app frustrating, particularly when a screen must load before a decision can be completed. I would avoid starting an important transaction in a place where I might lose connection or be interrupted, and I would keep my phone protected with its normal security controls.
For people who prefer cash-only routines, Payactiv may feel like an unnecessary extra layer. For someone who already uses a bank’s tools and has a stable emergency fund, the convenience may not justify changing habits. The strongest audience is the worker who values earlier access and is willing to monitor the consequences carefully.
Practical workflows that make the service less stressful
My preferred workflow begins before an emergency. I would install the app, understand the available screens, and decide what kind of expense would genuinely justify early access. That preparation matters because a person under pressure is more likely to accept the first available option without asking whether it solves the real problem.
Next, I would compare the amount I need with the amount I expect at the next regular payday. The key question is not simply “Can I access this?” but “What will my remaining cash flow look like afterward?” Writing the calculation in a note can help users who find on-screen figures difficult to hold in memory. It also gives a useful pause for anyone prone to impulse decisions.
I would then use the app for a specific purpose rather than treating it as a general spending balance. Paying an essential bill is easier to evaluate than making several small discretionary purchases that quietly add up. Afterward, I would check whether my normal budget still works and adjust upcoming spending if necessary.
Another useful habit is to review the app when calm and note any wording that I do not understand. Financial language can be tiring for people with reading difficulties, limited English proficiency, or cognitive fatigue. If a term, amount, or timing statement is unclear, I would not guess. I would seek an explanation through the app’s available support route or ask a trusted person to read the information with me.
These steps are not glamorous, but they turn Payactiv from a panic button into a controlled cash-flow tool. They also expose the central trade-off: convenience is valuable only when I preserve enough awareness to manage the following pay period.
Remaining barriers and points that deserve caution
The biggest barrier is eligibility and personal fit. Early access to earned wages is not the same as unrestricted access to income, and the experience depends on whether the worker can use the service in their employment situation. I would check that practical point before building an emergency plan around the app. A tool that cannot be used when needed is not a dependable substitute for savings or a confirmed support arrangement.
Another barrier is comprehension. A user may understand the headline amount but miss the significance of timing, deductions, processing steps, or the way an early-access decision affects later cash flow. I would never confirm an action based on a quick glance. This is especially important for users with dyslexia, memory difficulties, attention disorders, or limited financial literacy. Short, plain-language explanations and a predictable sequence would make a major difference, but the user still needs to verify the details presented on their device.
There is also an emotional barrier. When a person is worried about food, transport, rent, or utilities, even a clear interface can feel demanding. The app may reduce one kind of pressure while creating another if the user begins depending on access before every payday. I see that as the main reason not to describe Payactiv as a complete financial-wellness solution. It can support a goal, but it cannot replace stable income, a realistic budget, or emergency savings.
Privacy and device security deserve ordinary caution as well. I would use a personal device, keep the operating system updated, avoid entering financial information on public networks, and lock the phone. I would also make sure that anyone helping with accessibility understands which screen is being confirmed. Assistance should improve comprehension without turning control of a financial action over to someone else casually.
Finally, some users simply prefer a different approach. If I need detailed investment analysis, comprehensive household budgeting, or a long-term debt plan, I would choose a specialist finance tool. If I need a one-time emergency and have another safe option, I would compare that option carefully. Payactiv is focused, and that focus is its strength, but it also means it is not designed to be every kind of money app.
Who I would recommend it to
I would recommend Payactiv to an eligible worker who occasionally faces a short-term timing problem and wants to connect earned wages with broader financial goals. It is particularly appealing to someone who can make a clear plan, read confirmation details carefully, and resist turning early access into routine spending money.
I would be more cautious for anyone whose essential expenses already exceed regular income. In that case, repeated early access could hide the underlying gap and make each following pay period harder. I would also hesitate to recommend it as the only option for a person who needs extensive budgeting, debt counseling, or investment tools. The app can be part of a plan, but it should not be mistaken for the entire plan.
For accessibility-minded users, I would recommend testing it slowly rather than assuming the experience will suit every ability. Adjust the phone first, complete a low-pressure review of the interface, and confirm that amounts and timing are understandable. If reading, motor control, hearing, or concentration makes the process difficult, involve a trusted helper while keeping the final decision with the account holder.
My inclusive verdict on Payactiv
Payactiv is a focused finance app with a practical purpose: helping people reach earned wages earlier while keeping financial-wellness goals in view. I like that it addresses a real cash-flow problem rather than pretending every user needs a complicated financial dashboard. Its free price, Everyone age rating, broad adoption, and strong average rating make it worth considering, but those points do not remove the need to check eligibility, understand each action, and plan for the next payday.
From an inclusion perspective, I see a useful foundation rather than a universal answer. People can improve their experience with larger text, voice control, magnification, contrast settings, and a quiet environment, but system adjustments cannot solve unclear financial wording or an unsuitable cash-flow pattern. The app is most supportive when the user can understand the amount, purpose, and timing without rushing.
My final recommendation is simple: use Payactiv as a controlled bridge for a specific need, not as permission to spend ahead indefinitely. If that distinction fits your situation, it may be a helpful addition to your financial routine. If you need deep budgeting, long-term debt support, or a solution to an ongoing income shortfall, a different service or human adviser will probably serve you better. For the right worker, Payactiv turns a payday timing problem into a decision that can be planned instead of improvised.
Gallery
Payactiv Pros and Cons
- Early access to earned wages can help cover unexpected expenses.
- Works with participating employers and payroll systems.
- Includes budgeting tools to help track spending and plan ahead.
- May offer discounts
- cashback
- and savings opportunities.
- Provides a convenient mobile alternative to traditional payday loans.
- Availability depends on employer participation and eligibility requirements.
- Some services may include transaction
- transfer
- or membership fees.
- Frequent wage advances can make future paychecks feel smaller.
- Certain features may be limited by location or employer settings.
- Customer support response times may vary during busy periods.
Payactiv Frequently Asked Questions
What is Payactiv, and how does it work?
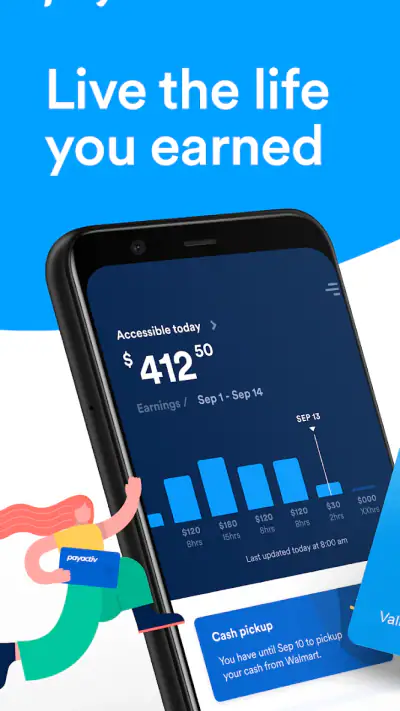
Payactiv is a financial wellness app that can give eligible employees access to part of their earned wages before the regular payday. After connecting with a participating employer, the app shows available earnings based on recorded work hours. Users may transfer money to a bank account, debit card, or other supported option, depending on their employer and location. Availability, limits, and fees can vary.
Who can use Payactiv?
Payactiv is generally available to employees whose companies offer Payactiv as an employee benefit. Downloading the app alone does not guarantee access, because eligibility depends on the employer’s payroll system, employment status, hours worked, and other verification requirements. During setup, you may need to provide personal information and confirm your identity before viewing earned-wage access or related financial tools.
How quickly can I receive money through Payactiv?
The delivery time depends on the transfer method you choose. Some supported options may provide funds quickly, while standard bank transfers can take longer, particularly outside business hours, on weekends, or around holidays. In my review, the app clearly presented available transfer choices, but users should always check the estimated arrival time and any applicable charge before confirming a transaction.
Does Payactiv charge fees for using its services?
Payactiv may offer certain features at no cost, while other services, such as specific transfer methods or optional financial products, may involve fees. The exact pricing can depend on your employer agreement, location, account type, and the destination selected for the funds. Before submitting a transfer, review the confirmation screen carefully so you understand the total cost and amount you will receive.
Is Payactiv safe to use, and what should I do if I have a problem?
Payactiv uses account verification and security measures designed to protect personal and financial information, but users should still choose a strong password, avoid sharing login codes, and keep the app updated. If a transfer is delayed, information appears incorrect, or you suspect unauthorized activity, contact Payactiv support promptly and notify your employer’s payroll or benefits department when the issue involves earned wages.














